Seven Stones · Buying decisions · Research checked 24 October 2026
Choosing between an apartment, townhouse or villa in Dubai? A family apartment has the stronger recent price signal in the sizes below. A well-bought villa faces a smaller share of next year’s scheduled new supply. Neither is an automatic winner: rents and the price you pay still decide the investment.
First, the wider market
The September snapshot shows both groups above last year’s prices, but softer than June. Rents also eased during the quarter.
The wider market
Dubai · September 2026
| Measure | Apartments | Villas + townhouses |
|---|---|---|
| Median sale / sq ft | AED 1,404 | AED 1,638 |
| Price change June → September | ↓ −2.4% | ↓ −2.3% |
| Price change Year-on-year | ↑ +2.2% | ↑ +4.1% |
| Rent change June → September | ↓ −3.8% | ↓ −2.3% |
Villas and townhouses are grouped in this market snapshot.
Apartment vs villa in Dubai: compare the bedrooms
The bedroom comparison tells a different story: sale prices and rents can move in opposite directions. Compare each size on the same row: sale prices on the left, rents on the right. Green means an increase; red means a decrease.
Over twelve months
12-month change to September 2026 · Dubai
| Property type | Sale price | Annual rent |
|---|---|---|
| 2-bed apartment | ↑ +3.38% | ↓ −8.68% |
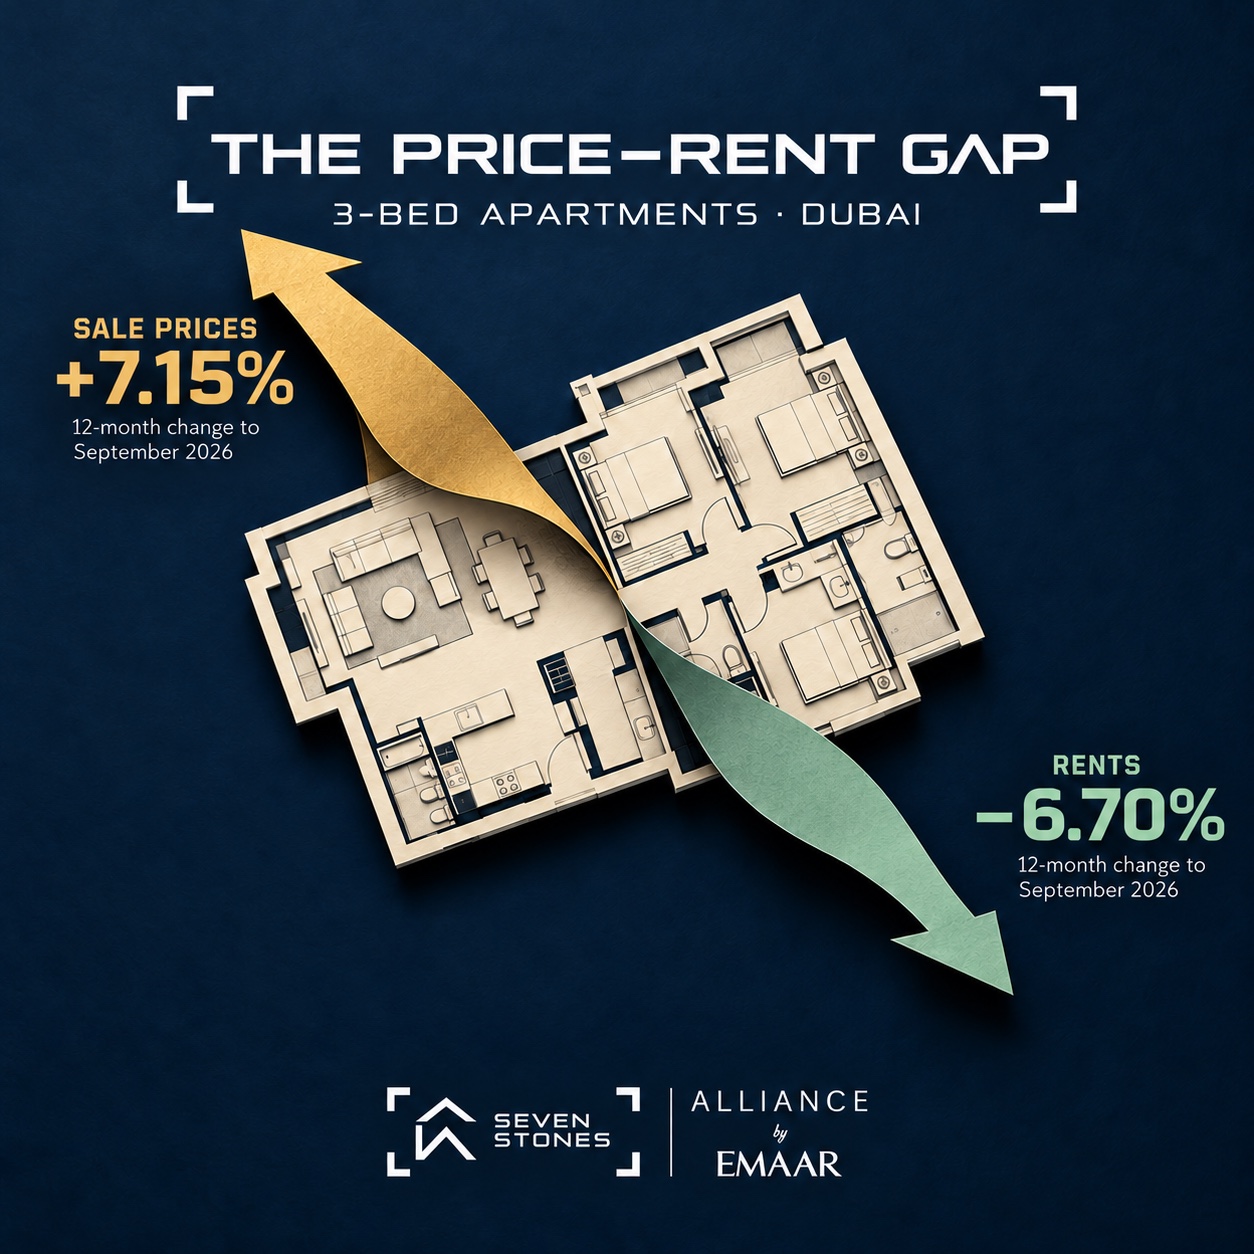
| 3-bed apartment | ↑ +7.15% | ↓ −6.70% |
| 3-bed villa | ↓ −0.48% | ↓ −2.75% |
| 4-bed villa | ↑ +0.68% | ↓ −2.56% |
Over three months
3-month change to September 2026 · Dubai
| Property type | Sale price | Annual rent |
|---|---|---|
| 2-bed apartment | ↑ +0.17% | ↓ −2.27% |
| 3-bed apartment | ↑ +0.55% | ↓ −1.30% |
| 3-bed villa | ↓ −0.76% | ↓ −1.40% |
| 4-bed villa | ↑ +0.06% | ↓ −0.93% |
Price and rent levels
September 2026 · AED per sq ft
| Property type | Sale price / sq ft | Annual rent / sq ft |
|---|---|---|
| 2-bed apartment | 2,039 | 115 |
| 3-bed apartment | 2,615 | 128 |
| 3-bed villa | 1,673 | 83 |
| 4-bed villa | 1,792 | 89 |
All completion statuses. Separate citywide sale and rental samples; these are not total unit prices or a matched-home yield.
The three-bedroom apartment shows more price growth and less recent rent easing than the two-bedroom. The four-bedroom villa has held up better than the three-bedroom villa on both recent price and rent movements. These are shortlist signals, not forecasts.
Townhouses: a community example, kept separate
A separate citywide townhouse series was not verified. Jebel Ali Village provides a useful local example, based on an agent’s published analysis of registered transfers and leases. It must not stand in for all Dubai townhouses.
Townhouse comparison
Jebel Ali Village only · Q2 → Q3 2026
| Measure | 3-bed townhouse | 4-bed townhouse |
|---|---|---|
| Q2 median sale | AED 4.28m | AED 5.35m |
| Q3 median sale | AED 4.50m | AED 5.68m |
| Price change Q2 → Q3 | ↑ +5.1% | ↑ +6.2% |
| Q3 annual rent | AED 200k | AED 245k |
| Indicative gross yield | 4.4% | 4.3% |
One community, not all Dubai townhouses. Gross yield uses separate rent and sale medians, before costs; it is not a net or matched-unit return.
What is scheduled to arrive in 2027?
Scheduled homes · Dubai · calendar 2027
136,815 homes. Mostly apartments.
90.5%123,880 apartments
9.5%12,935 villas + townhouses
Scheduled, not guaranteed handovers. Calendar 2027; villas and townhouses are combined, with no bedroom split.
For Dubai Creek Harbour or Dubai Hills Estate, check the competing buildings and layouts due near your unit. For a townhouse in The Valley or a home in Emaar South, check the relevant phase and handover wave.
Our shortlist for the next twelve months
Price momentum: 3-bed apartment
It leads the bedroom groups checked here on annual price growth. Prefer a layout and position with few close substitutes. Falling rents mean yesterday’s asking rent should not justify today’s purchase price.
Supply angle: 4-bed villa
It has been steadier than the smaller villa in the recent bedroom series. The wider landed pipeline is smaller than apartments’, but check local completions before paying a scarcity premium.
The townhouse decision stays local. The Jebel Ali Village example favours the three-bed slightly on indicative gross income, and the four-bed on quarterly median price movement. It does not establish a citywide winner.
For an investment, compare the actual rent, buying costs, service charges and maintenance on each shortlisted unit. For off-plan, include the payment dates and whether rent will start within your holding period.
Our current reading: start with a three-bedroom apartment for the stronger observed price trend, or a four-bedroom villa for the landed-supply angle. We cannot reliably name the highest-returning unit for the coming year from broad indices. The winning purchase still needs a sensible entry price and unit-level checks.
Does rising property value mean rising rent?
No. The apartment series shows price growth alongside softer rents. A buyer can pay more while receiving less income.
Are the supply figures guaranteed handovers?
No. Completion dates can move, and the published pipeline does not separate bedrooms.
Can I use these figures as a rental-yield quote?
No. Citywide sale and rental samples are not matched homes. Calculate the return for the actual unit, with its running costs.
Which apartment size has the stronger price trend?
The three-bedroom apartment leads the four bedroom groups compared here, with a 7.15% price increase over the twelve months to September 2026. That historical trend does not guarantee the next year’s return.
Does the 2027 pipeline separate villas from townhouses?
No. The verified figures group villas and townhouses together. They cannot tell us which of the two will receive fewer new homes, or how many will have three or four bedrooms.
Is the twelve-month change the same as year-to-date?
No. Twelve months to September compares with September last year. Year-to-date would need a December baseline; no unverified YTD figure is used here.